California Gov. Gavin Newsom signed a first-in-the-nation law into effect on Friday, which lawmakers say will push back on “secretive” wildfire risk algorithms used by insurance companies.
The legislation, SB 429, requires all documentation, programs, data, and algorithms of the model relating to wildfire risk to be publicly available. The new regulations go against the state’s current rules that exempt insurance companies from disclosing that information, which they use to set insurance rates.
The law also calls on the California Department of Insurance and the state’s universities to create a wildfire safety and risk mitigation program to assess risks and drive mitigation efforts across federal, state, and local partners, according to the law’s text.
“Most of California’s buildings are not properly mitigated against wildfires,” a report from the California Department of Insurance said earlier this year. “Extreme weather-fueled wildfires are also expanding or intensifying the wildfire risk map. This is a problem at the intersection of fire science, climate science, wildland firefighting, home hardening, fire risk mitigation efforts, and the economics of risk, loss, and the cost of recovery. As a multifaceted problem, this crisis demands a collaborative, multisector solution.”
The move was applauded by consumer protection organizations in the state, who say the new model will give homeowners, renters, and small businesses access to information they need to understand their own wildfire risk and the ability to make their communities safer.
“Homeowners are fed up with insurance companies’ black-box models that penalize consumers for fire risk but refuse to explain how they calculate it,” Consumer Watchdog Executive Director Carmen Balber said in a press release on Monday. “Even when they do everything to protect their homes from wildfires homeowners face extreme price hikes or lose their insurance completely. A fully transparent wildfire model will level the playing field and empower consumers to keep their insurance and make their homes and communities safer.”
A new report out of Colorado found that homeowners in the state have the sixth-highest insurance costs in the nation, primarily in wildfire-prone areas. Costs aren’t expected to fall anytime soon.
More than 321,000 homes in the state face “moderate or higher” wildfire risk, around 12% of the state’s total housing units. Report author Caroline Conley Norris pointed to increased development in wildfire-prone areas as a major reason for the increase.
Many insurers have also decided to remove themselves from certain areas of the Colorado market since wildfire risk is too high, but not nearly at the same rate as other disaster-prone states. Norris said that may be because Colorado is less regulated than other states.
“It could mean that insurers are able to cover their risk (in Colorado) in other ways. They can raise their premiums or adjust their terms in a way that makes them feel comfortable,” Norris told Colorado State University. “We’re seeing a lot of non-renewal in places like California and Florida, where insurers are seeing repeated giant losses from these hazard events and they aren’t able to raise their prices fast enough.”
Colorado lawmakers just opened up their FAIR insurance coverage plan to residential property owners. The plan is meant to act as a last-resort insurer when homeowners can’t get any other coverage.
Currently, 33 other states have FAIR plans, but each state sets up its plans differently. Norris said it’s harder to get approved for a FAIR plan in Colorado, but she believes that’s because lawmakers were trying to keep the state budget in mind.
“It will be interesting to see what happens here in Colorado,” Norris said. “When homeowners in some high-risk areas have really expensive insurance options but aren’t eligible for the FAIR plan, will they opt to not buy home insurance and self-insure? We’re seeing some affluent homeowners do that in Florida because paying for repairs out of pocket is a better option than buying prohibitively expensive insurance.”
Insurance isn’t the sexiest topic to either write or read about, but an extreme weather-driven downtrend of insurance agency availability is tightening the noose on an already suffocating national housing market.
The U.S. had its highest number — 28 — of annual billion-dollar weather disasters in 2023, including the Lahaina wildfire, California flooding, and Tropical Cyclone Idalia in Florida, according to a NOAA report. Homeowner insurance agencies’ response to the continually rising costs has either been to drastically increase their insurance rates or to back out from certain areas entirely.
The dire situation first made national headlines last year when numerous agencies, including State Farm, Allstate and Farmers, either paused or placed heavy restrictions on policyholders in wildfire-prone areas in California. Seven of the state’s top 12 insurance agencies have put the restrictions into effect as of November, ABC News reported.
Colorado appears to be the next state to face extremely tight, or nonexistent, homeowner insurance policies caused by increasing wildfire threats. The Durango Herald recently reported the average homeowner insurance premium in the state increased 51.7 percent between January 2019 and October 2022. Meanwhile, some new homeowners in the state are having trouble getting policies at all.
“A State Farm insurance agent in Durango wrote a couple a quote for homeowners insurance. But six days before closing, the State Farm office called to inform the Bowmans that it could not write them a policy,” said the Herald’s story on a couple who recently moved to Durango. “Geico, Travelers, other State Farm agents – all of them turned him down.”
Local insurance businesses in Durango reportedly have “plummeted” by 20 to 30 percent since insurers changed their policies sometime last September. Agents in Colorado expect the insurance issues to keep piling up in the years to come. A Climate Change in Colorado Assessment report for 2024 found climate change and increased atmospheric warming will lessen streamflows and make the state drier, leading to more and worse wildfires.
“Studies have uniformly indicated substantially worsened wildfire risk for Colorado by the mid-21st century compared with the late 20th-century, as additional warming further increases fuel dryness and enhances fire ignition and spread,” the report from the Colorado Climate Center said.
Climate change info — by Colorado State University
California Insurance Commissioner Ricardo Lara said this week that insurance companies in the state will soon be allowed to factor in climate risks including wildfires in their insurance rates — if they increase their underwriting in at-risk areas to wean consumers off state-funded coverage.
Reuters reported that in the last year or two, seven of the state’s top 12 insurers have paused or restricted new business, including State Farm and Liberty Mutual, and the government’s Fair Access to Insurance Requirements (FAIR) Plan, intended as an insurer of last resort, has grown to a 3 percent share of California’s market.
Firefighters on the Dixie Fire at Greenville, CA, 2021. Jay Walter.
“We are at a major crossroads on insurance after multiple years of wildfires and storms intensified by the threat of climate change,” Lara said.
Unlike other states, according to an ABC News report, California does not allow insurance companies to consider current or future risks when setting the rate for an insurance policy. Companies can consider only what’s happened on a property in the past to set the price.
And insurers say that restriction makes it difficult to accurately price the risk.
On Thursday, Lara said California will write new rules to let insurers look to the future when setting their rates. “Modernizing our insurance market is not going to be easy or happen overnight,” he said. “We are in really unchartered territory and we must make difficult choices when the world is changing rapidly.”
The rule change is not all good news — it could mean higher rates for homeowners who have already seen dramatic increases. Eight insurance companies in California have requested increases of at least 20 percent this year, according to the California Department of Insurance.
Harvey Rosenfield, the author of a 1988 ballot proposition that regulates insurance rates, said Lara’s announcement “will dramatically increase homeowner and renter insurance bills by hundreds or even thousands of dollars.”
El comisionado de Seguros de California, Ricardo Lara, dijo esta semana que a las compañías de seguros del estado pronto se les permitirá tener en cuenta los riesgos climáticos, incluidos los incendios forestales, en sus tarifas de seguro, si aumentan su suscripción en áreas de riesgo para que los consumidores dejen de recibir cobertura financiada por el estado.
Reuters informó que en el último año o dos, siete de las 12 principales aseguradoras del estado han detenido o restringido nuevos negocios, incluyendo State Farm y Liberty Mutual, y el Plan de Acceso Justo a los Requisitos de Seguro (FAIR, por sus siglas en inglés) del gobierno, pensado como una aseguradora del último año. resort, ha crecido hasta alcanzar una cuota del 3 por ciento del mercado de California.
Several major insurance companies have stopped accepting California homeowners for new policies because of growing wildfire risks. As the number of fires in the state increases and other factors escalate, insurance companies worry about the risk — and the expense.
In 2022 there were over 5,000 wildfires, according to Cal Fire, that burned about 118,000 acres. Already this year 4,337 fires have burned over 114,560 acres.
Residents in high-risk fire areas or hurricane regions need homeowners’ insurance — and lenders require it. No insurance, no home loan. More people are moving into the interface, costing insurance companies too much to repair and replace houses while battling inflation, said Janet Ruiz with the Insurance Information Institute. Two insurance giants withdrew from California’s home insurance marketplace, explaining that increasing wildfire risk and soaring construction costs have resulted in their decisions to stop writing new policies in the state. State Farm announced last week it would stop accepting applications for all business and personal lines of property and casualty insurance, according to the Associated Press. The company cited inflation, a challenging reinsurance market, and rapidly growing catastrophe exposure.
“We take seriously our responsibility to manage risk,” State Farm said. “It’s necessary to take these actions now to improve the company’s financial strength.”
Unlike heavyweights State Farm and Allstate, which declined to sign new homeowners in the state, AmGUARD and Falls Lake will also drop their existing policyholders.
Allstate, another insurance powerhouse, announced in November it would pause new policies for homeowners, condos and commercial properties in California to protect current customers.
Homeowners may have to turn to the California FAIR Plan, which provides basic fire coverage, if they aren’t able to find an insurer that will cover fire expenses. The high-risk pool known as the FAIR Plan is not a government entity or a state program. Taxpayers do not fund the FAIR Plan — it’s supported by all carriers licensed to do business in California, which spreads the risk among all the insurance carriers. Because the FAIR Plan is a high-risk policy, people should expect to pay more than they would for a standard homeowner policy.
The San Francisco Standard reported last week that two more companies quietly left the California market, further narrowing options for those trying to insure their home or purchase one with a mortgage.
AmGUARD Insurance — a subsidiary of Berkshire Hathaway GUARD Insurance Companies — will withdraw its homeowners and personal umbrella programs, and Falls Lake Insurance will also end its homeowners program. Both companies made the announcements July 21 in little-noticed filings submitted to the state regulator. AmGUARD and Falls Lake are the latest insurers to end or limit their business in the state during the past year.
Unlike heavyweights State Farm and Allstate, which declined to sign new homeowners in the state, AmGUARD and Falls Lake will also drop their existing policyholders. Safeco plans to drop 950 policies in October in San Francisco and the East Bay.
An SFGATE report noted that State Farm held the most policies in the California property market in 2021, and the company experienced about a 60 percent loss that year.
We were talking with Jennings about the making of the film when the text arrived. He shared the news, and remembered, as a filmmaker and resident of Portland, Oregon, those days of wind, smoke and firestorms, of so many lost homes, and of when the film’s team first saw the footage of sparking power lines that ignited the destructive fires.
The news settled and we turned back to the other topics that he’s been focusing on: the vital dialogues of science, the challenging transitions of policy and funding, and the role of insurance as a potential pivot point to help us face wildfire’s risks to homes.
At the moment we were talking about the film itself, and the continuing conversations that the film prompts.
“Elemental: Reimagine Wildfire” is streaming on Apple TV, Google Play, and Amazon beginning June 13. Select your platform at elementalfilm.com/streaming-pre-sale.
From initial screenings of the film. Jennings learned that the film sells out in communities where there are effective partnerships working to face wildfire issues. In these communities, Jennings said, the audience may have “a little bit of experience with fire, and they’re curious what to do. They want ideas on how to move forward, they’re feeling vulnerable and concerned. And fire folks are excited about the film too and want to share it. Yet it’s hard for firefighters to say, there’s a limit to what we can do.”
Which is one component of the theme in Elemental. That what we’ve been doing isn’t solving the problems. “We point out the limits to suppression,” though Jennings added that “There’s not a world where we’re not going to fund fire suppression.” And the role that fire professionals play in an ongoing paradigm shift is key. In making the film and during screenings, Jennings observed the “incredible and rare social capital of firefighters” and how their observations of the fire challenge is helping communities change. He was also pleased that the film caught enough of the nuances of fire management and fire science so that it resonated with firefighters (as well as fire survivors and politicians).
The role and voices of firefighters, cultural burners (firelighters), fire scientists, community members and policy makers will all be required in reimagining fire (and all are represented in the film). “We need to change the way we’re thinking about the cultural narrative. When we say the problem is in the forest, it’s not a sufficient answer. The forest is a value at risk, not a solution [to be implemented by logging]. If we can separate fire safety conversations from forest product industry conversations. … if we can separate the conversations more, to let fire safety be its own topic and goal, then the film will be a huge win. And then we can have a more nuanced conversation that takes in the science.”
While suppression will always be a component, Jennings observed that what we fund when it comes to fire and fuels management needs to be focused on the values at risk, often the homes, which may not benefit from a distant forest treatment (and he notes that brush and grass fires, and home-to-home burning, can be as destructive as “forest” fires). Or, for that matter, a logging project packaged as fire safety.
Jennings pointed out that federal fuels management funding is often limited to federal lands, when the dollars would be more effective if they went directly to fire-hardening houses. “In California, the best numbers we can find show that only two of every hundred dollars is spent on the the home. The rest is spent on vegetation management. That’s part of what we help communicate in the film” … including the benefit of focusing on the home ignition zone, building on the work of Jack Cohen, the National Fire Protection Association (NFPA) and the Insurance Institute. of Business and Home Safety (IBHS). And to remember “that in one year we lost more homes in Paradise to fire than were built in California.”
Rebuilding homes is very expensive and fraught with legal and practical issues. “We’ve found ourselves in the insurance space,” Jennings said when the film first began to screen, in part because of ongoing work that Jennings and film producer/editor Sara Quinn are doing for the PBS Terra show “Weathered.”
Director Trip Jennings and producer/editor Sara Quinn filming at the El Dorado Fire for ‘Elemental.’ Photo: Ryan Walsh.
“It’s the story of what’s going on for so many people rebuilding after fires. A lot of people who got dropped from insurance after a fire, for instance, if their house didn’t burn all the way down. A lot of recovery efforts seem to help those who have time and financial resources.”
And the rates rise. “We talked to someone who paid $1000 total, now their insurance totals $4500. I might spend that money to improve my home, not on insurance.” When it comes to fuels treatment, he said “I think we need to see that where the money goes. Even if it goes to private homes, that is a huge private benefit but everyone is safer if we spend money preparing homes for wildfires. If we cant get out the loop that we can only spend [fuel treatment and preparedness funds] on public lands.”
With some insurers leaving home insurance markets, Jennings wondered if the challenge of identifying the specific cost of wildfire risk, and charging for that through the home insurance process, may be a watershed moment. Again he echoed the ability of the film to reach targeted audiences. With showings to insurance professionals and risk managers he anticipates they may see the value to more clearly identify homes and home clusters that are ready to coexist with fire, and to offer price adjustments for those prepared homes. “We began with FireWise and now the key may be more granular initiatives. Homes are beginning to be counted with the “Wildfire Prepared Home” program being rolled out by IBHS [in a California pilot program], but whether the neighbors are prepared isn’t counted yet. There’s no idea how to model and price the individual risk within a neighborhood.” Though the IBHS program is a key step that may allow homeowners and insurers to rate a home’s wildfire preparedness, which may also mesh with a wildfire risk-rating process by the First Street Foundation along with NFPA’s “Outthink Wildfire” strategy.
Of course, this week’s news and next week’s developments aren’t in the film, but Jennings believes the film is evergreen, in part because of the conversations it prompts (such as those we’ve had with Jennings over the past two months).
There is this and more in the film, of course, including an examination of the role of cultural burning in re-working our relationship with fire. And if our relationship with fire is complex, it is also, as the title reminds us, elemental. As elemental as the reminder that Jennings shared: the key to coexisting with fire begins within the five-foot zone adjacent to the house. “Since the 2008 WUI code, the science around the first five feet has developed a lot. Maybe it’s more important than any single thing.”
UPDATE 06/02/2023 — Allstate and Farmers join State Farm in denying new homeowner policies in California. State Farm quit selling new homeowner policies on Saturday, and now a second major carrier, Allstate Insurance, has confirmed it ended new homeowners’ policies in the state last year. On top of that, ABC-7 News reported that Farmers Insurance is now limiting policies for new customers. All three companies are still serving existing customers, and more than 100 other companies are still issuing new homeowners’ policies, but homeowners across the state will have a tougher time buying coverage.
State Farm will no longer provide home insurance to new California customers because of wildfire risks and increased construction costs. The company quit accepting new applications for business and personal lines and casualty insurance in California, USA TODAY reported.
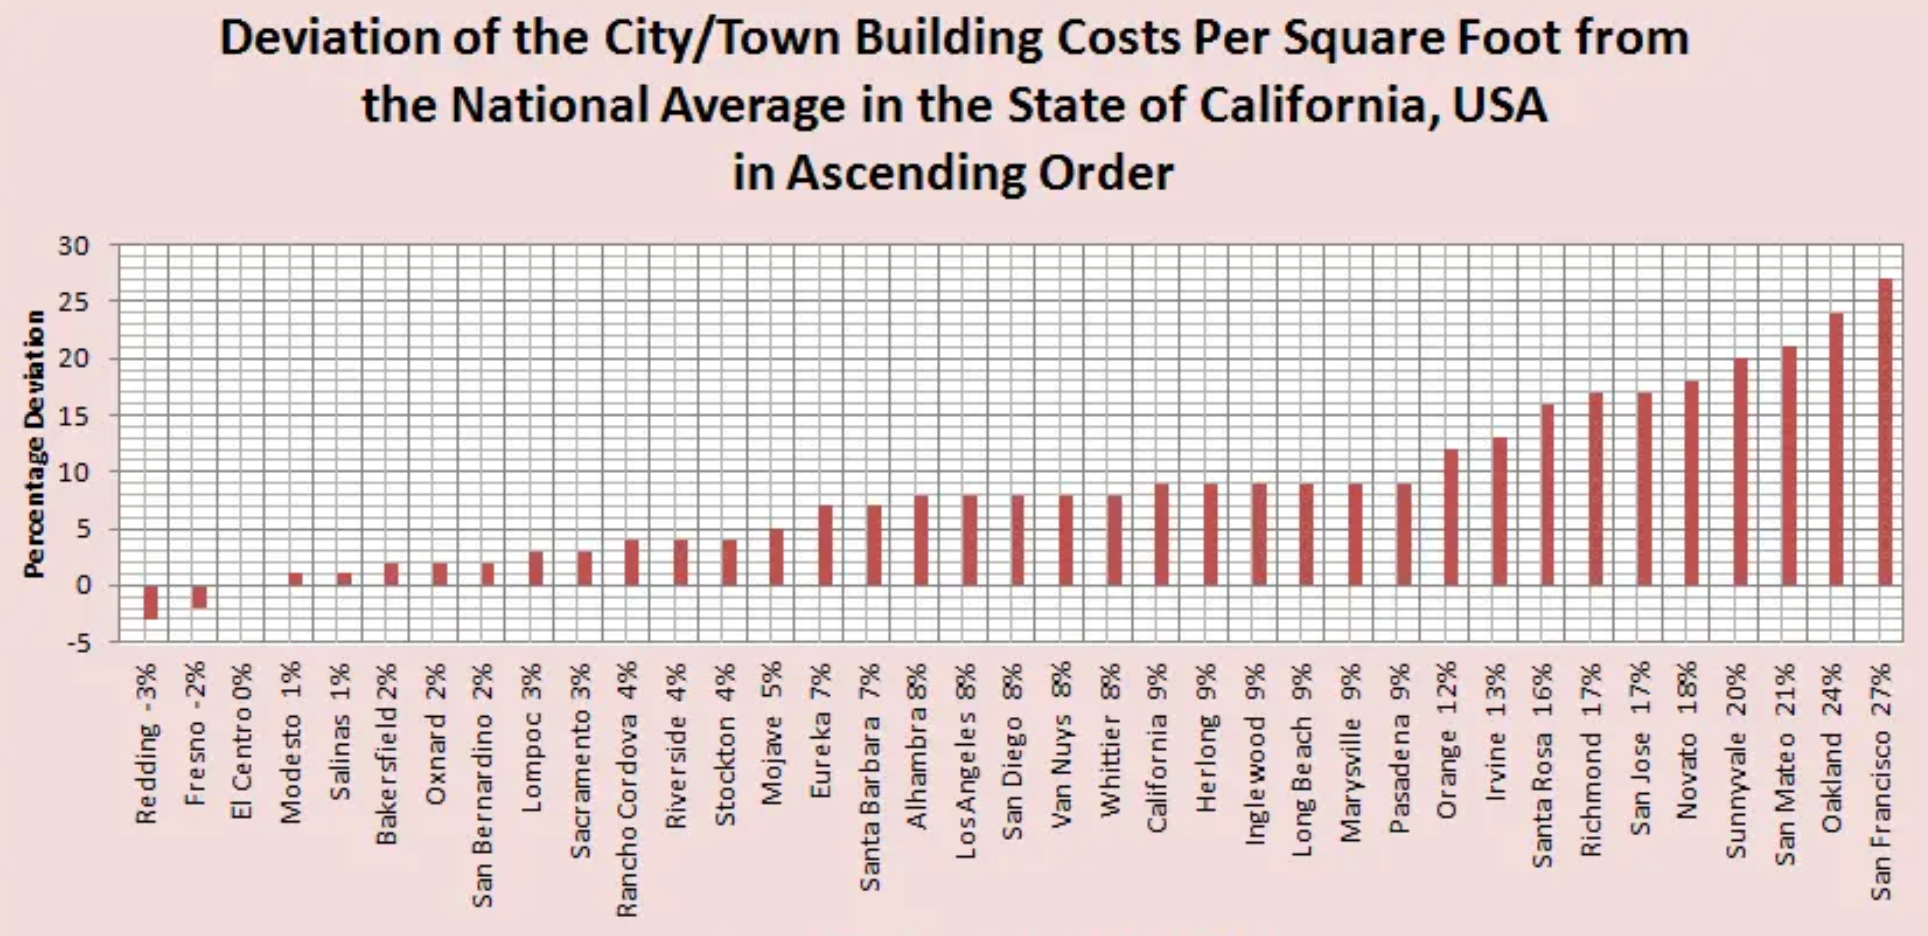
Estimation QS Building Cost Estimating, Construction, Outdoor Projects and Activities
State Farm said it will still work with the California Department of Insurance and lawmakers and will still serve existing customers.
The Oregonian reported that last year, California became the first state to require insurance premium discounts for those with wildfire protection safeguards at homes or businesses. That change was in response to soaring insurance costs for customers in high-risk areas.
“State Farm General Insurance Company made this decision due to historic increases in construction costs outpacing inflation, rapidly growing catastrophe exposure, and a challenging reinsurance market,” the company said in a statement.
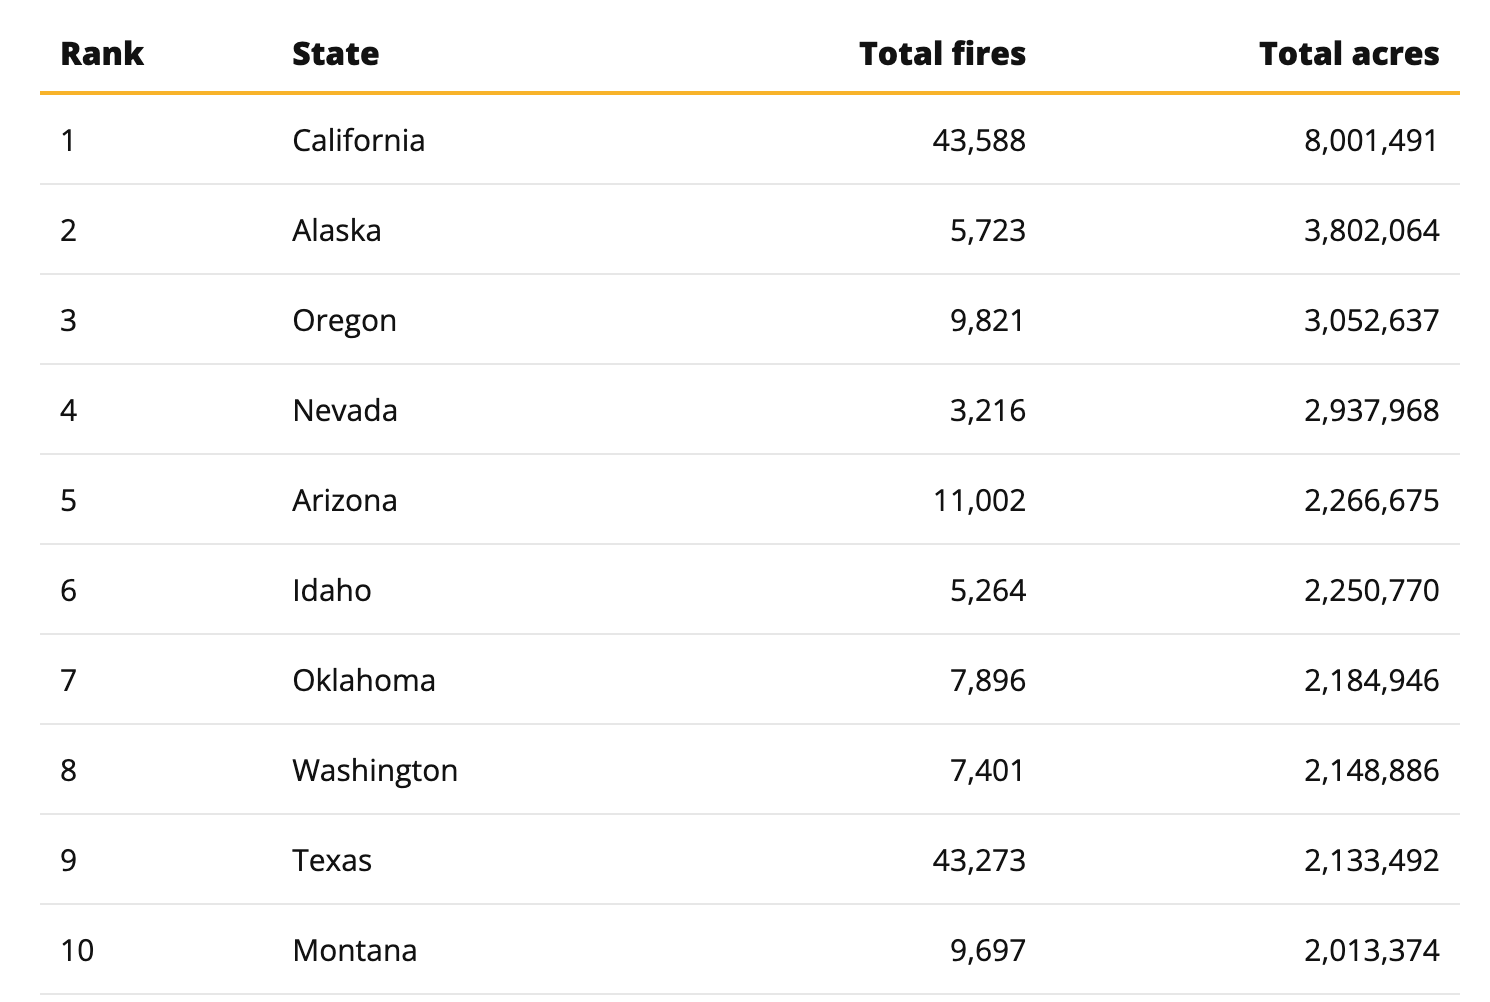
Top ten states by acres burned, 2016-2020.
CNN reported that scientists and California officials blame the climate crisis for the intensity of fire seasons. About 25 percent of the state’s forestland burned in the last 10 years — more than triple the previous decade.
The factors behind Illinois-based State Farm’s move are beyond the agency’s control, Michael Soller with the California Department of Insurance said. State Farm, with its affiliates, is the largest provider of auto and home insurance in the U.S.
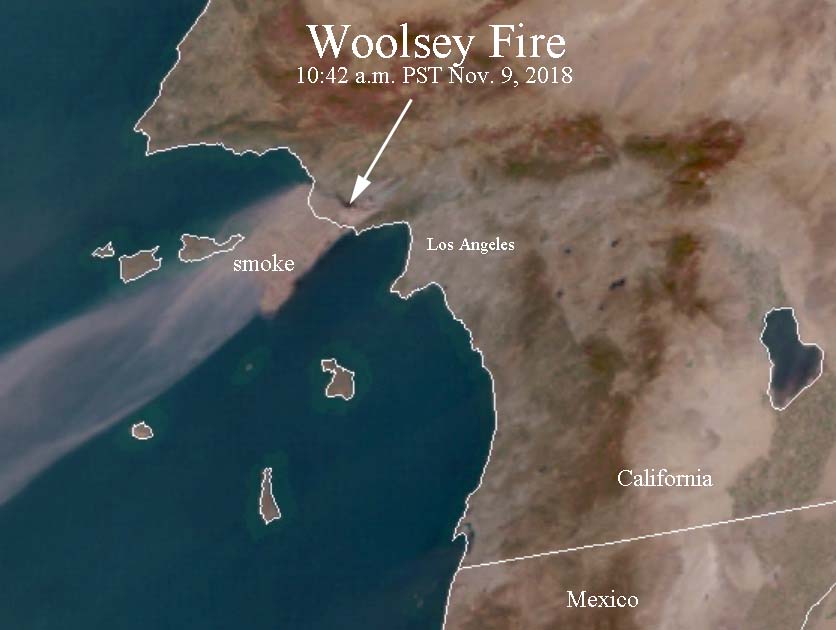
Satellite photo showing smoke from the Woolsey Fire at 10:42 a.m. PST November 9, 2018. Click to enlarge.
For the last 12 years we have been aware of insurance companies sending fire engines to protect high-valued homes covered by their policies when a wildfire approaches. Companies such as Chubb figure keeping a multi-million dollar home from burning is less expensive than paying to rebuild it, so they contract with Wildfire Defense and other companies to send firefighters to their customers properties when smoke is in the air.
The tricky part is intermixing the private crews with the existing incident management organization. Some jurisdictions view the insurance company crews as personnel that need to be protected, rather than fellow firefighters engaged in the fire fight. This became very evident during the Woolsey Fire in November when CAL FIRE prohibited the private engine crews from accessing their customers’ homes, including mansions in Malibu, California.
Below is an excerpt from the Malibu Times:
…While benefits seem obvious for insurance companies, statewide fire officials point out they complicate firefighting efforts for central command, since they cannot communicate readily with rank-and-file crews. Now, in the fallout of the Woolsey Fire—where resources were spread so thin many homes did not see any fire engines at all—questions are being asked about why private crews were turned away.
Malibu resident Ron Krisel, who is insured by USAA (only available to active, retired and honorably discharged members of the U.S. military), was eligible for the services of a private firefighting crew. However, he was notified by USAA that when their crew checked in with the joint command for the Woolsey Fire, they were told by CAL FIRE that they would not be allowed to come into Malibu and, something to the effect that, if they disobeyed, they would never be allowed in during a fire from now on.
Krisel’s house burned down the day after the fire came through—a casualty of still-blowing embers. He feels strongly that if the private crew contracted by USAA had been allowed to come in, his house would’ve been saved—they would’ve kept an eye on the burning embers and hot spots and put them out before the house caught fire. County firefighters never showed up.
When The Malibu Times contacted Scott McLean, public information officer for CAL FIRE Woolsey Fire, to ask why, he said he wasn’t familiar with this particular incident, and would only be able to talk about their policy in general.
McLean verified that private fire companies must check in with the authorities at the joint command to show documentation from the insurance company and the address of the specific house.
“It’s a common thing—no big deal. We rarely turn them away,” McLean said. “But if there’s an evacuation order for the area the house is in, they cannot come in.” That’s the most obvious reason why the crew coming to Krisel’s house was turned away—the Malibu evacuation order must have already been in effect.
Our opinion:
Private engine crews can be helpful in keeping certain high-value structures from burning during a rapidly spreading wildfire when there are not enough government resources to protect every home. However, if they have no communication with the incident management organization which does not have any knowledge of their location, mission, or capabilities, it can throw a monkey wrench into an already chaotic situation.
CAL FIRE, the U.S. Forest Service, and the other large organizations involved in wildfire suppression need to sit down with the insurance companies and agree on some standard operating procedures. The Incident Management Team needs to know what the private crews are doing and where, and the private crews need to have direct communication with the Team.
One day, when all firefighting resources are carrying equipment that makes it possible to track their location, this will become much easier — and safer. The federal and state agencies need to get off their butts and implement these tracking systems.